

Cashli: Cash Advance & Rewards
4.1

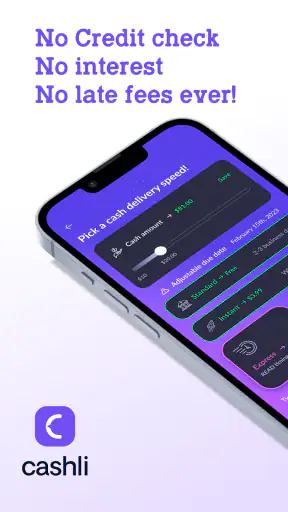
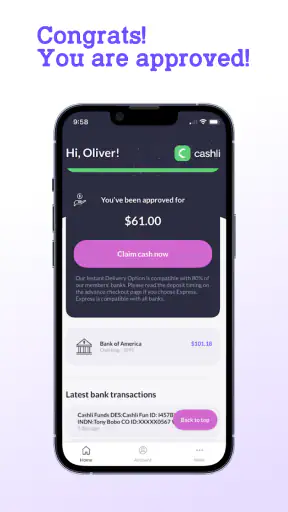
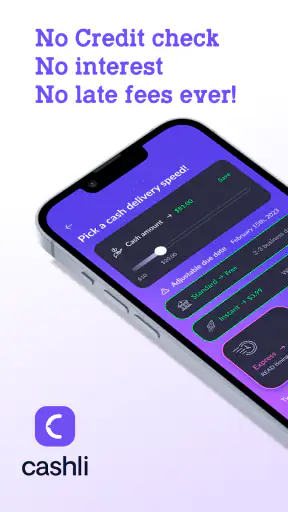
I approached Cashli: Cash Advance & Rewards as a practical finance app rather than a general budgeting tool. Its purpose is straightforward: help eligible users seek a small cash advance when an immediate expense is more urgent than the next payday, while also presenting rewards as part of the experience. That focus makes it potentially useful in a narrow moment, but it also means I would not treat it as a complete answer to ongoing money problems.
The app is free to install, carries an Everyone age rating, and comes from Cashli Funds. It has reached more than 100 thousand installs, with an average rating of 4.1 from roughly 4.9 thousand ratings and 2.8 thousand written reviews. Those figures suggest that many people can get through the basic experience, although they should not be mistaken for a guarantee that every applicant will receive money or find the process equally comfortable.
How Cashli feels to use when money is already stressful
Readability and navigation in a high-pressure finance app
My first concern with any cash-advance service is not visual polish; it is whether I can understand what I am being asked to do before I make a financial decision. Cashli’s central promise is easy to grasp, which is a good starting point. The app is aimed at a specific need instead of burying the main purpose under a large collection of unrelated financial tools.
That simplicity matters for people who are tired, worried, or trying to solve a problem between other responsibilities. A user checking the app during a late commute or while dealing with an overdue household bill should not have to learn complicated financial vocabulary first. I found the most useful approach was to move slowly through each screen, read every explanation, and avoid treating a prominent action button as an automatic recommendation.
There is an important difference between readable navigation and fully transparent borrowing. A short path to an application can feel welcoming, but a short path can also encourage a rushed decision. I would pay close attention to any information about repayment, eligibility, timing, account requirements, and the conditions attached to rewards before continuing. The easiest screen to tap is not always the most important screen to understand.
For readers with dyslexia, limited reading stamina, or difficulty processing dense financial language, the best personal workflow is to pause after each stage and summarize the commitment in plain words. If I cannot explain when the money must be repaid or what the total obligation means, I would not proceed yet. That habit is more valuable here than simply judging whether the interface looks clean.
Cashli is currently listed as version 1.0.19 and requires Android 8.0 or later. That makes it relevant to people who keep an older Android phone instead of replacing it frequently. At the same time, compatibility alone does not tell me whether every device presents text, controls, or system prompts equally well. After installation, I would check the display at the user’s normal text size and confirm that no important wording becomes difficult to read.
Motor and sensory considerations during an application
Financial applications can be challenging for people with limited dexterity because they often combine scrolling, text entry, consent screens, and time-sensitive attention. I would not recommend trying to complete a Cashli request while walking, carrying a child, or using one hand on a crowded bus. A stable surface and enough time reduce the chance of tapping the wrong control or overlooking a condition.
Users with tremors or reduced precision may benefit from enlarging the device’s display settings before starting, using an external keyboard where the phone supports it, and reviewing each field before moving forward. I would also keep the phone charged and avoid switching repeatedly between apps, since interruptions can make it harder to remember where I was or whether a step was completed.
For people with low vision, contrast and text scaling are especially important in a finance context. I would test the app with the phone’s normal accessibility settings rather than assuming that a default layout suits everyone. Larger text can sometimes cause wrapping or push an explanation below the visible area, so I would scroll deliberately instead of relying on the first screenful. If a key condition becomes clipped, crowded, or ambiguous, that is a practical reason to stop and seek clarification.
People with hearing loss should not have to depend on audio cues to understand a financial action. I would look for written confirmations and visible status information, especially after submitting details or waiting for a decision. People sensitive to motion, flashing, or busy visual effects can likewise keep the phone’s system motion settings comfortable and take a break if the process becomes tiring. I cannot treat Cashli as having a specific accessibility certification, but these device-level adjustments can make the experience more manageable.
Screen readers introduce a different test. A person using TalkBack needs labels that announce controls in a sensible order and enough context to distinguish an informational message from a button that creates a commitment. I would encourage screen-reader users to review each announced element carefully and, where possible, have a trusted person help verify the meaning of a repayment or consent screen. That is not a criticism unique to Cashli; it is a sensible safeguard whenever borrowing is involved.
Situational access: when the app makes the most sense
The strongest use case is a short-term emergency where a relatively small amount could prevent a more serious immediate problem and the user already understands how repayment will fit into the next part of the budget. The store summary frames the service around getting up to 150 dollars now, so I would view it as a limited bridge rather than income, savings, or a substitute for a regular emergency fund.
Imagine a person whose essential transport expense arrives just before payday. They open Cashli from an older Android phone, increase the text size, read the terms carefully, and compare the repayment obligation with the money they expect to receive. In that situation, the app may be convenient because it concentrates attention on the immediate request instead of requiring a visit to a branch. The convenience is useful only if the user can repay without sacrificing food, housing, medication, or another essential bill.
Another realistic scenario involves a user who has difficulty traveling to a bank because of fatigue, mobility limitations, caregiving duties, or an unpredictable work schedule. A phone-based application can remove travel and waiting-room barriers. That does not remove the need for clear information, but it can make the first step more accessible for someone who cannot easily use traditional in-person services.
The rewards angle may appeal to people who enjoy earning something while using a finance product, but I would keep it secondary. Rewards should never be the reason I borrow money. I would first decide whether the advance itself is affordable, then examine what the rewards involve and whether pursuing them adds extra time, attention, or personal-data decisions. A reward is not a discount on repayment unless the app clearly says so.
Cashli is less suitable for someone who needs long-term debt management, detailed spending categories, bill negotiation, investment guidance, or a conventional savings plan. A budgeting app may be better for finding recurring leaks, while a bank or credit union may be preferable for users seeking an established relationship and broader financial products. For repeated shortfalls, a nonprofit debt counselor or a conversation with a trusted adviser is more appropriate than repeatedly relying on advances.
What I would check before requesting money
I would begin by identifying the exact problem the money is meant to solve. If the answer is vague, such as “I am always short,” an advance is unlikely to fix the underlying issue. If the answer is a specific essential expense, I would write down the expected repayment date and compare it with rent, utilities, food, transport, and medication that must be paid first.
Next, I would read every screen rather than assuming that “free” describes the entire borrowing experience. The app itself is free to download, but that does not automatically explain every possible condition associated with an advance or a reward. I would look for clear wording about eligibility, repayment, timing, and any action that might affect the final outcome. If a sentence feels deliberately vague, I would treat that as a reason to pause.
I would also prepare the phone environment for privacy and concentration. Using a private connection, avoiding public conversations while entering financial details, and locking the screen afterward are sensible steps. People with cognitive disabilities or anxiety may find it helpful to use a written checklist: purpose of the advance, amount requested, repayment expectation, essential bills due first, and the point at which they will stop if the terms are unclear.
One useful but easily missed trade-off is speed versus review time. The appeal of a cash-advance app is that it may feel faster than a traditional option, yet speed increases the cost of an error. I would rather spend a few extra minutes checking a repayment condition than accept money I cannot comfortably return. That is particularly important for users who process information slowly or who are making decisions under pressure.
Remaining barriers that can affect inclusive use
The biggest barrier is financial rather than technical: a person may be able to navigate the app perfectly and still be unable to use an advance safely. Someone with irregular income, unstable housing, or existing repayment obligations may be especially vulnerable to turning a single emergency into a cycle. Cashli’s convenience should therefore be judged against the user’s full budget, not just the urgency of today’s expense.
Digital access can create another layer of difficulty. A person may have an older phone that meets the Android requirement but limited storage, a weak connection, a damaged screen, or little privacy. Someone sharing a device with family members may also be uncomfortable entering sensitive information. These are not minor inconveniences when the app is handling a financial request.
Language and comprehension can matter just as much as font size. A user who is not confident reading financial English may understand the headline purpose but miss a qualification in the detailed wording. I would not rely on automatic translation for a borrowing decision without checking the original meaning carefully. If a trusted interpreter helps, that person should explain the terms without taking control of the account or receiving private credentials.
There is also an emotional barrier. The promise of immediate relief can make people feel that declining is impossible. I appreciate the directness of Cashli’s purpose, but directness needs to be balanced with room to reconsider. Anyone feeling pressured should close the app, write down the obligation, and compare alternatives before submitting anything. A friend, family member, employer advance, bank option, or local assistance program may be safer depending on the situation.
For users with accessibility needs, I would judge the app by what happens when something goes wrong: an interrupted connection, an unclear status, a mistyped detail, or a screen that does not work well with assistive settings. Clear written feedback and an understandable way to recover are more important than decorative design. I would keep records of submission screens and confirmations, without exposing private information, so I could track what I had done.
How it compares with ordinary alternatives
Compared with a standard budgeting app, Cashli is more focused on immediate access to money and less suited to understanding spending over time. A budgeting tool usually helps me plan before an emergency arrives; Cashli addresses the emergency itself. If my problem is recurring overspending, budgeting is the better first move. If the problem is a one-off gap and repayment is realistic, Cashli may be more relevant.
Compared with a traditional bank or credit union, a mobile cash-advance service can feel more convenient for someone who cannot visit a branch or does not want a broad financial relationship. The trade-off is that I have to be more careful about the exact terms and the limits of the product. A bank may be preferable when I need a larger, structured loan, face-to-face assistance, or a wider set of account services.
Compared with borrowing from a friend or family member, Cashli may feel less socially uncomfortable, but a formal financial obligation can still create pressure. Compared with a credit card, the right choice depends on the user’s existing terms and repayment habits; neither should be treated as free money. Compared with a payday lender, a user should still read Cashli’s conditions closely rather than assuming that a smartphone interface automatically makes the borrowing safer.
The rewards component also changes the comparison slightly. A rewards app may be worthwhile when the activity is genuinely optional and easy to understand, but it should not distract from the cost and timing of an advance. I would never increase a request, delay repayment, or share more information simply to chase a reward whose practical value I have not calculated.
Who should use it, and who should skip it
I can see Cashli helping an adult who needs a modest, short-term bridge, has a clear repayment plan, can read and review the conditions, and values completing the process from a phone. It may also suit someone whose mobility, schedule, or location makes in-person financial services difficult. The free installation and broad age rating make the app easy to consider, but those points do not replace affordability checks.
I would skip it if I already depend on advances to cover ordinary living costs, if repayment would force me to miss another essential bill, or if I am unsure when my next reliable income will arrive. I would also choose another route if I need detailed financial coaching, a structured long-term loan, or hands-on accessibility support. A person who cannot independently understand the obligation should wait for trusted assistance rather than rush through the process.
My practical recommendation is to install it only when I have a defined reason, a quiet moment, and a written repayment plan. I would adjust the phone for comfortable reading, move through the screens at my own pace, and stop immediately if the wording around the advance or rewards is not clear. That process makes the app more useful without pretending that convenience removes financial risk.
An inclusive verdict on Cashli
Cashli Funds has built a finance app with a clear emergency-oriented purpose, and I like that its basic idea can be reached from an Android phone rather than requiring a branch visit. Its current version, 1.0.19, and support for Android 8.0 or later also make it accessible to people who are not using the newest hardware. In my experience, the most important accessibility question is not whether the app looks simple, but whether each user can understand and control the financial decision.
The app works best as a carefully considered short-term option, not as a permanent solution to an income gap. Its rewards should remain an optional extra, while the advance deserves the user’s full attention. People with visual, motor, hearing, cognitive, or situational needs can improve the experience with device settings, written checklists, and extra review time, but they should still expect to evaluate every screen for themselves.
My final view is cautiously positive for the right person: someone facing a specific, manageable emergency who can repay without harming essential spending. I would not recommend it automatically to someone in chronic financial difficulty or anyone who feels rushed, confused, or unable to verify the obligation. Cashli is most inclusive when it gives users enough clarity and control to say yes—or confidently walk away.
4.1
2.79K Reviews
Pros
- Fast application process with clear eligibility information
- Rewards can add extra value for frequent users
- Useful budgeting tools help track repayment obligations
- Simple interface is easy to navigate for new users
- Available support resources can clarify account questions
Cons
- Approval and advance amounts may vary by applicant
- Fees and repayment terms require careful review before accepting
- Not available in every state or region
- Late repayment could lead to additional costs or account issues
- Requires access to personal and financial information


